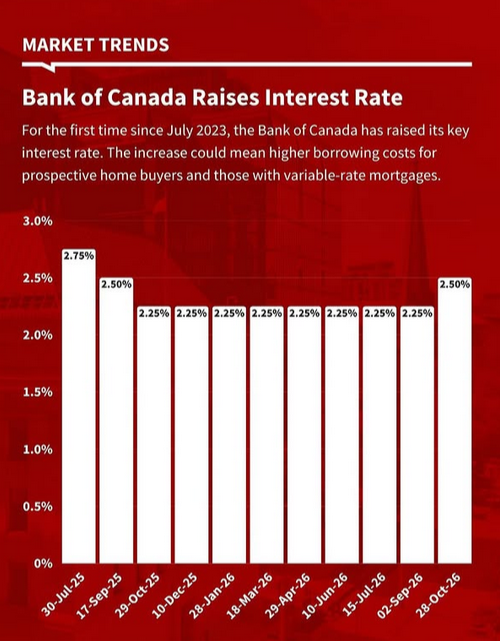
For the first time in more than three years, the Bank of Canada has raised its policy interest rate.
Canada’s central bank announced Wednesday, October 28, that it’s increasing its key interest rate by 25 basis points to 2.5%. The move follows seven consecutive rate holds and marks the Bank’s first interest rate adjustment since October 29, 2025.
The last increase came on July 12, 2023, when the Bank raised its rate to 5%.
For prospective home buyers and homeowners, the announcement raises questions about borrowing costs, mortgage payments and whats next for Canadas housing market.
Why did the Bank of Canada raise its interest rate?
Much of the Bank’s reasoning comes down to one concern: inflation.
While Canada’s economy has performed better than expected, the ongoing conflict in the Middle East has kept global energy prices elevated. Beyond filling up your own vehicle’s gas tank, higher fuel costs make it more expensive for businesses to produce and transport goods.
Inflation has hovered around 3% since April and the Bank of Canada states its expected to reach approximately 3.5% by the end of 2026, above the Bank’s 2% target.
Meanwhile, Canada’s economy grew 3.3% in the second quarter, with growth estimated at roughly 2% in the third quarter. However, new U.S. tariffs could slow that momentum, and the Bank expects housing activity to remain relatively weak.
By raising interest rates, the Bank states it hopes to prevent higher energy costs from spreading further into the prices Canadians pay for everyday goods and services.
And another increase isn’t off the table. The Bank included this in its statement released on Wednesday.
What does the interest rate increase mean for Canadian home buyers and homeowners?
A quarter-percentage-point increase might not sound particularly large, but its effects depend on whether you’re buying a home, paying down a mortgage or approaching renewal.
For homeowners with fixed-rate mortgages
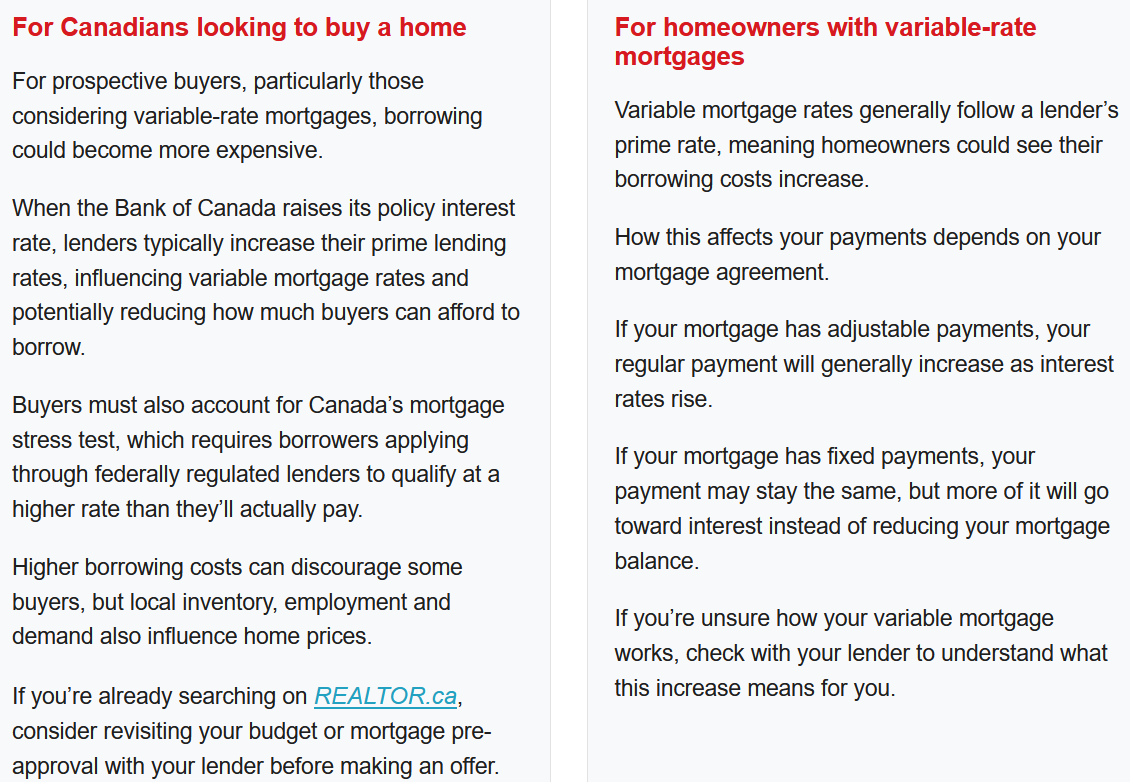
For Canadians with fixed-rate mortgages, there’s no immediate change to existing mortgage rates or scheduled payments.
Your rate is locked in for the duration of your term, whether that’s three years, five years or another length.
Fixed mortgage rates are influenced heavily by Government of Canada bond yields, which reflect broader financial conditions and expectations about future interest rates.
Bond yields have risen in recent months, prompting some lenders to increase their fixed mortgage rates. Unlike variable rates, a Bank of Canada increase doesn’t automatically mean fixed rates will rise.
What mortgage rates are available in Canada right now?
The Bank of Canada’s policy rate isn’t the same rate you’ll receive when applying for a mortgage.
Lenders determine mortgage rates based on market conditions, mortgage terms and individual financial circumstances.
Even before Wednesday’s announcement, rising bond yields had been pushing some fixed rates higher, while variable rates remained closely tied to lenders’ prime rates.
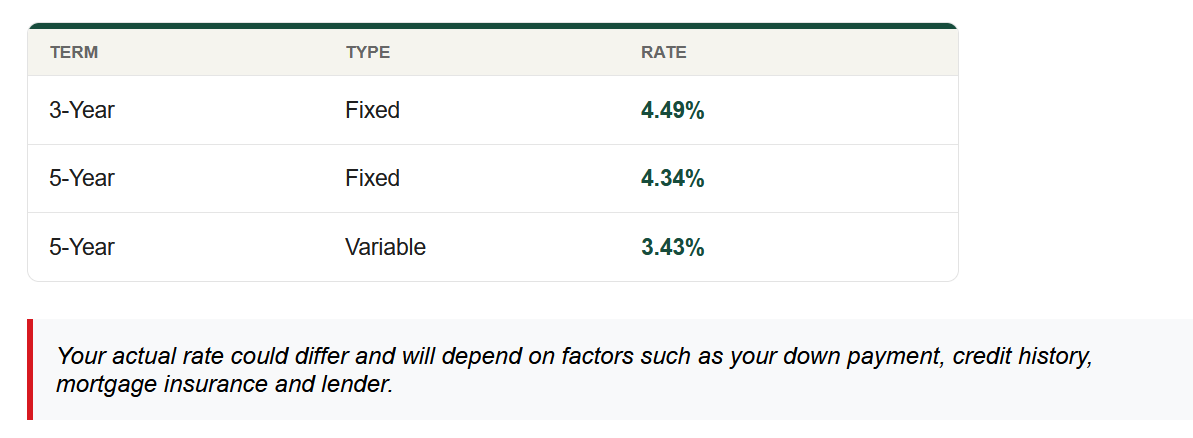
You can compare current mortgage offers through resources such as Ratehub.ca, but advertised rates can change quickly.
Ratehub is currently advertising the following featured rates:
Is your mortgage up for renewal soon?
If your mortgage term is ending within the next several months, it’s worth exploring your options early.
Your existing lender may send you a renewal offer, but you aren’t required to accept it without comparing what’s available elsewhere.
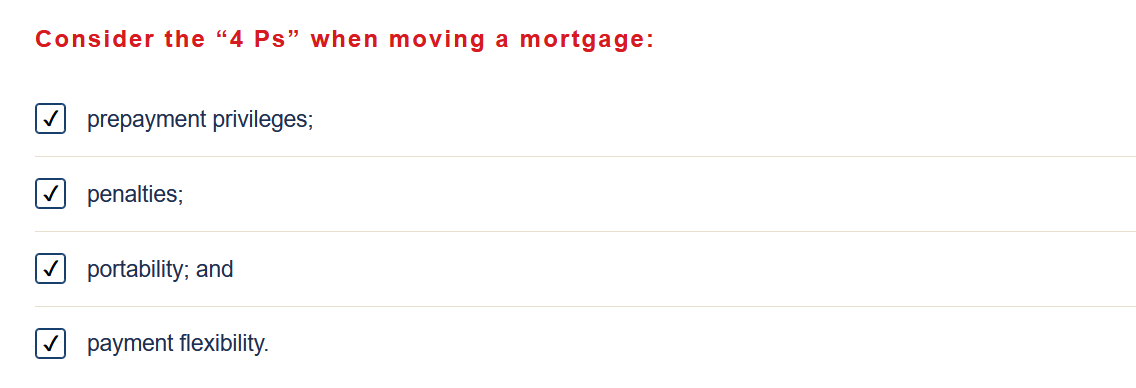
A mortgage broker or lender can help you compare rates and terms based on your circumstances.
Here’s what you need to know if your mortgage is up for renewal.
Will the Bank of Canada raise interest rates again?
That’s the question many Canadians will be watching over the coming months.
The Bank of Canada expects inflation to average around 3% in 2027 before returning to its 2% target around the middle of 2028.
With elevated energy prices, U.S. tariffs and uncertainty surrounding economic growth, future decisions will depend on how these pressures develop.
While additional increases remain possible, the Bank has indicated it intends to proceed carefully.
The next scheduled Bank of Canada interest rate announcement is December 9, 2026.
Why working with a REALTOR® is important
Interest rates are only one part of the home buying and selling equation.
Next Gen Realty Team can help you understand local market conditions, compare recent sales and assess available inventory.
Whether you’re buying or selling, our experience can help you make informed decisions about your next move, even as borrowing costs change.