RSS

New property listed in Osoyoos

I have listed a new property at 24 Wood Duck Way in Osoyoos. See details here

BUILD NEW IN A GREAT LOCATION – NO STRATA FEES! Opportunity awaits in this exciting new subdivision, offering smaller, manageable lots with the freedom of no strata fees. Build your dream home yourself or let us build it for you! Ideally located close to schools, golf, shopping and the firehall, this centrally located neighbourhood puts everyday amenities within easy reach. Step outside your door and enjoy excellent walking and hiking trails, with mountain views providing a scenic backdrop. Whether you're looking to build a home for yourself, create a low-maintenance property or secure a lot in a growing new neighbourhood, this is an opportunity worth exploring. Choose your own builder or ask us about building options. New subdivision • No strata fees • Mountain views • Walking & hiking trails at your doorstep • Close to schools, golf & shopping. (id:2493)

Read

New property listed in Osoyoos

I have listed a new property at 26 Wood Duck Way in Osoyoos. See details here

BUILD NEW IN A GREAT LOCATION – NO STRATA FEES! Opportunity awaits in this exciting new subdivision, offering smaller, manageable lots with the freedom of no strata fees. Build your dream home yourself or let us build it for you! Ideally located close to schools, golf, shopping and the firehall, this centrally located neighbourhood puts everyday amenities within easy reach. Step outside your door and enjoy excellent walking and hiking trails, with mountain views providing a scenic backdrop. Whether you're looking to build a home for yourself, create a low-maintenance property or secure a lot in a growing new neighbourhood, this is an opportunity worth exploring. Choose your own builder or ask us about building options. New subdivision • No strata fees • Mountain views • Walking & hiking trails at your doorstep • Close to schools, golf & shopping. (id:2493)

Read

New property listed in Osoyoos

I have listed a new property at 22 Wood Duck Way in Osoyoos. See details here

BUILD NEW IN A GREAT LOCATION – NO STRATA FEES! Opportunity awaits in this exciting new subdivision, offering smaller, manageable lots with the freedom of no strata fees. Build your dream home yourself or let us build it for you! Ideally located close to schools, golf, shopping and the firehall, this centrally located neighbourhood puts everyday amenities within easy reach. Step outside your door and enjoy excellent walking and hiking trails, with mountain views providing a scenic backdrop. Whether you're looking to build a home for yourself, create a low-maintenance property or secure a lot in a growing new neighbourhood, this is an opportunity worth exploring. Choose your own builder or ask us about building options. New subdivision • No strata fees • Mountain views • Walking & hiking trails at your doorstep • Close to schools, golf & shopping. (id:2493)

Read

New property listed in Osoyoos

I have listed a new property at LOT B Grizzly Place in Osoyoos. See details here

Experience the beauty of the Okanagan from this exceptional 4.3 acre property on sought after Grizzly Place. Offering breathtaking panoramic views of Osoyoos Lake and the surrounding mountains, this expansive parcel provides the perfect setting to create your dream home and enjoy the peace, privacy, and natural beauty that make Osoyoos so special. With generous space to bring your vision to life, the property offers plenty of room for a custom residence, outdoor living areas, gardens, and more. Imagine waking up to stunning lake and mountain views, spending summer evenings outdoors, and taking in spectacular Okanagan sunsets from your own private retreat. Adding to the property's appeal, its convenient proximity to the Osoyoos Fire Hall offers quick access to emergency services and an added sense of reassurance. A drilled well is already in place, and with no timeline to build, you have the freedom to plan and create at your own pace. (id:2493)

Read

New property listed in Oliver

I have listed a new property at 129 2450 Radio Tower Road Road in Oliver. See details here

A One-of-a-Kind Cottage at The Cottages on Lake Osoyoos! This exceptional 3-BDR, 3-BATH cottage with loft offers a custom-built main-floor primary suite and an impressive array of upgrades. The chef’s kitchen and open living area create a spacious great room featuring a custom fireplace with wireless media hub, soaring open-beam cathedral ceiling and an upstairs loft office overlooking the living area. Enjoy year-round comfort in the insulated sunroom with a proper exterior door. The upgraded kitchen features GE Cafe appliances, quartz countertops, a built-in Keurig coffee maker in the fridge, true self-cleaning oven and warmer drawer. The primary suite offers a walk-in shower with rain head. Additional features include no carpet throughout, LED lighting with dimmer switches, laundry room sink, extra-large hot water tank, central vacuum and water softener. Outside, enjoy an extra-large patio and extended driveway with parking for up to four vehicles and home complete with gutters on north side at entryways. The pie-shaped lot provides generous space within your property lines, creating excellent privacy and separation from neighbouring cottages. Ideally located close to the lake and clubhouse, yet far enough from the main pathway and green space to enjoy a quieter setting away from the summer activity. A truly special cottage offering comfort, privacy and exceptional upgrades in one of Osoyoos’ sought-after lakefront communities. (id:2493)

Read

New property listed in Rock Creek

I have listed a new property at 3590 #3 Highway in Rock Creek. See details here

10.43 FLAT IRRIGATED ACRES • NO ZONING • 120 GPM WELL • MULTIPLE ACCOMMODATIONS A rare and versatile 10.43-acre flat, irrigated property classified as No Zoning, offering an exceptional combination of land, water, living accommodations, storage, workshops and flexible space. The 1,420 sq. ft. 2-bedroom, 1-bathroom home features a chef-inspired kitchen open and comfortable living space, with one wood-burning stove and one propane stove for heating. The home also has R-60 blown-in insulation for added energy efficiency. Additional accommodations include a 1-bedroom cabin and a 1-bedroom RV with full hookups, each with its own separate septic system — ideal for family, guests or additional living space. There is plenty of room for hobbies, projects and business needs with a double-car garage/workshop, perfect for crafting, a home-based business, vehicles or equipment. The impressive 40’ x 30’ Quonset provides even more workspace and storage and features a mezzanine office, while two sea containers add additional secure storage. Water is a major asset, with a high-producing 120 GPM well equipped with two pumps: a 3/4 HP shallow jet pump for domestic use and a 10 HP deep submersible pump dedicated to irrigation. With flat irrigated acreage, abundant water, multiple accommodations, extensive outbuildings and workshop space — all on a No Zoning property — this is a truly versatile opportunity for those seeking space, flexibility and a rural lifestyle. (id:2493)

Read

Financial Programs Available to Help First-Time Home Buyers


If you’re like most Canadians, buying a home is probably one of the biggest investment you’ll ever make. But for first-time home buyers, just saving up enough money for the down payment can take years or even decades to accomplish.

Thankfully, Canada’s federal and provincial governments offer several different programs designed to support first-time home buyers by offsetting some of the costs associated with buying a home, and helping them purchase their first property.

Down payment requirements for first-time buyers

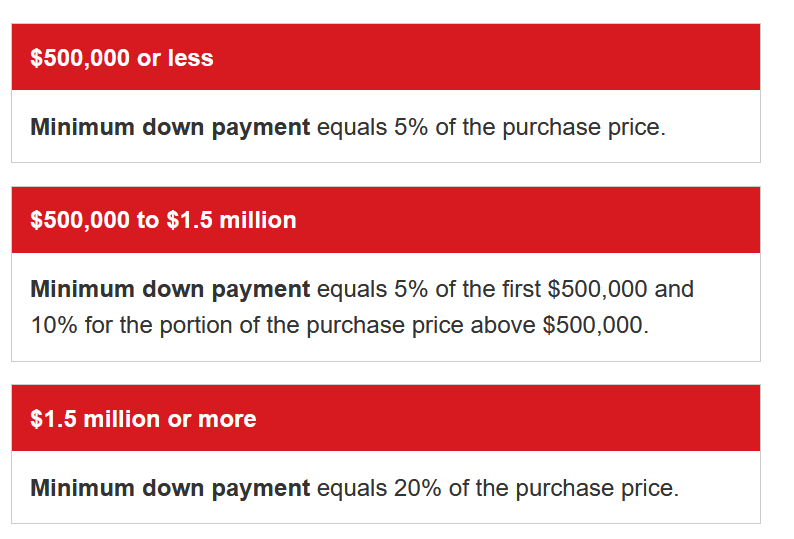
For most first-time home buyers, one of the biggest hurdle is usually saving for the down payment.  In Canada, the required down payment amount is determined by the purchase price of the home as follows:

First-time home buyers naturally pour their energy into saving for a down payment. But the full cost of buying a home goes beyond that. Closing costs, land transfer taxes, legal fees, and other expenses, it can be a lot to absorb all at once. That’s where the financial programs available to first-time buyers can make a real difference. When you understand what’s out there and combine those programs strategically, you can often get into a home sooner than you think, with less saved up front than you expected.

If your down payment is less than 20% of the price of your new home, you’ll also have to get an insured mortgage, which can add anywhere from 0.6 to 4.5% to the purchase price.

The amount of money you put toward your down payment can also affect the type of mortgage you get, and the interest rate you’ll have to pay. In general,the larger the down payment, the less interest you’ll pay on your mortgage

Once you have a clear picture of your down payment, your next step should be to get pre-approved for a mortgage. RBC’s online pre-approval can be completed in a few easy steps and will provide you with your mortgage amount and interest rate with no impact to your credit score or commitment to proceed.  A pre-approval is helpful to have prior to house hunting as you can act quickly on a property you want to buy when you already know what you can afford.

The RRSP Home Buyers’ Plan (HBP)

The Home Buyers’ Plan (HBP) is a federal program that lets eligible buyers withdraw up to $60,000 from their Registered Retirement Savings Plan (RRSP) to put towards their down payment when they buy or build a home for themselves, or for a relative with a disability.

Anyone who’s never owned their primary residence before, or who hasn’t lived in a primary residence they (or their spouse or common-law partner) own in the last four calendar years, is eligible to take part in the program. Any amount you withdraw must be repaid within 15 years to remain tax-free.

Couples can also both take part in the HBP at the same time if they buy or build a home together. This allows married or common-law first-time buyers to access up to $120,000 as a down payment on their first property.

First-Time Home Buyers’ Tax Credit (HBTC)

The First-Time Home Buyers’ Tax Credit (HBTC) is a non-refundable credit that gives first-time buyers a rebate of up to $1,500 on their income taxes when they, or their spouse or common-law partner, buy a home in Canada.

Also known as the Home Buyers’ Amount (HBA), the HBTC can help offset the costs of buying a whole range of eligible property types, from new and existing single-family and semi-detached homes, to condos, apartments, townhouses, housing co-ops and mobile homes.

GST/HST new housing rebate

For new builds, the federal government also offers a rebate on the GST/HST for anyone who buys a newly built or substantially renovated home as their primary place of residence. The rebate also applies when buying shares in a co-op or hiring a contractor to substantially rebuild or renovate your existing home.

The HST rebate on new homes is a program that can significantly improve a homebuyer’s cash flow, not just at the time of purchase, but for years to come. By reducing the overall amount that needs to be financed, it lowers monthly mortgage payments and has a meaningful, lasting impact on a client’s financial well-being.

Unfortunately, the GST/HST rebate only applies to homes with a fair-market value of $450,000 or less. But if your new home qualifies, you can receive a rebate of 36% of the GST charged on the home, up to a maximum of $6,300.

The GST/HST rebate only applies to the federal part of the HST paid on a new home. But some provinces also offer a similar rebate on the provincial portion of the tax.

As of March 2025, the GST on new builds for first-time home buyers has been eliminated. The full rebate, worth up to $50,000, applies to new builds valued at or under $1 million, with a partial, graduated rebate available on homes between $1 million and $1.5 million.

Buying a pre-construction home from a builder or building your own home comes with different financing options and processes that you can learn about here.

First Home Savings Accounts (FHSA)

The First Home Savings Account (FHSA) is a registered savings plan that lets first-time buyers save up to $8,000 a year, tax free, to buy or build a home. For the purposes of the program, “first-time buyers” include anyone who hasn’t lived in a primary residence they (or their spouse or common-law partner) own in the last four calendar years.

As a savings vehicle, the FHSA combines the benefits of both a Registered Retirement Savings Plan (RRSP) and a Tax-Free Savings Account (TFSA).

Like an RRSP, contributions to your FHSA can be used as a deduction on your income taxes, to reduce the amount of tax you owe. But like a TFSA, the investments inside your FHSA also grow tax-free, so you won’t have to pay any tax when you withdraw the money to buy a property.

Once you open a FHSA, you can contribute the maximum annual amount for up to five years. This would allow a first-time buyer to save up to a lifetime maximum of $40,000 to put towards their down payment, or up to $80,000 in the case of a married or common-law couple.

You can also carry forward any unused contribution room, up to a maximum of $8,000, but only to the following year,; it doesn’t accumulate beyond that. And if you’re not quite ready to buy, you can keep your FHSA open for up to 15 years.

First-time buyers who take advantage of both an FHSA and the Home Buyers’ Plan (HBP) could withdraw $100,000 or more (in the event that their FHSA investments increase in value) from their registered savings for a down payment without any tax implications. For a couple, the total amount doubles to $200,000 or more.

A First Home Savings Account is a great way to grow your savings tax-free while also reducing your taxable income, stretching your savings further and getting you into you first home sooner. As a first-time homebuyer this program is essential to minimize the financial stress of buying your first home.

Provincial and territorial programs

Several provinces, territories and municipalities also offer their own grants, rebates, tax credits and other programs to support home buyers, including first-time buyers. This includes programs like:

To find out which assistance programs and incentives are available in your area, check the housing section of your provincial or territorial government website, and contact your local municipal office or connect with a Mortgage Specialist near you.

How the pros can help

For most first-time buyers, simply navigating your way through all these different programs can be a daunting prospect. So if there’s anything you’re not sure about, why not ask Eileen or Jessee?

In addition to answering your questions and pointing you towards the programs you may be eligible for, they can walk you through each and every step of the home buying process, and help you find a home that perfectly fits your needs, your preferences—and budget.

Read

New property listed in Osoyoos

I have listed a new property at 8710 JUBILEE Drive in Osoyoos. See details here

Move-in ready family home in a sought-after neighbourhood—just a short walk to the town centre and beach! This well-kept home offers three bedrooms and two bathrooms , with thoughtful updates throughout. The kitchen features upgraded countertops, while the bathrooms have been refreshed. New laminate flooring, door trim, and lighting create a clean, modern feel. A spacious sunroom and covered wrap-around deck extend the living space and create a wonderful setting for relaxing or entertaining in every season. The finished basement offers excellent potential for an in-law suite or your creative ideas. The large, level backyard is complete with a great gazebo and plenty of room for children, entertaining, gardening, or adding a pool. Central air conditioning and a water softener provide added comfort and convenience. Newer roof, single-car garage, and RV parking round out this excellent package. A fantastic opportunity for families, retirees, or anyone looking for space, location, and easy living. (id:2493)

Read

4 Things to Do Before Applying for a Mortgage

While the journey to first-time homeownership can be full of dizzying highs and lows, understanding the mortgage process can make the trip a lot smoother.

Once you’ve applied and been pre-approved for a mortgage you can start your home search with confidence, knowing what you can afford.

There are generally four things first-time home buyers should do before applying for a mortgage:

  1. Establish your home buying team

  2. Budget beyond the home purchase price.

  3. Get pre-approved for a mortgage

  4. Organize your financial statements

Let’s take a more in-depth look at what you need to know when prepping for a mortgage application.

First, what is a mortgage and how does it work?

In simple terms, a mortgage is a loan given by a bank or mortgage lender used to buy real estate. It typically involves multiple parties who all play an essential role in the application process, such as:

  • the lender (this could be a bank, credit union or private institution);

  • mortgage advisor; and

  • the borrower (or buyer).

The buyer uses funds from a mortgage loan to pay the lender for the property and the buyer repays any money borrowed, plus applicable interest and fees, over a set duration at regular intervals.

A portion of each payment is used to pay down the amount borrowed (also known as the principal) and a portion of the payment is applied to interest. The mortgage is registered on the property with the applicable provincial or territorial land registry office.

In many cases, the buyer can move into the new home as soon as the closing is complete (although the terms of the sale/purchase agreement can sometimes specify a later move-in date).

Below are some other important terms related to mortgages.

📅 Amortization period

This is the length of time it takes to pay off a mortgage in full.

📈 Interest rate

This is the cost you pay to borrow money. It can be fixed or variable. A fixed rate stays the same for the duration of your mortgage term, giving you predictable payments. A variable rate fluctuates with the lender’s prime rate, so your mortgage payment can fluctuate as the lender’s interest rate goes up and down.

💳 Payment frequency

The number of payments you make over a year is known as the payment frequency. Payments can be made monthly, bi-weekly, or weekly. Some lenders also allow for double-up payments which let you make additional payments on top of your regularly scheduled payment, helping you pay down your principal faster.

The way in which a mortgage is structured is unique to the financial situation of each borrower. A mortgage agreement can be impacted by many factors, including credit score, debt-to-income ratio, and salary. It’s important to speak with a mortgage advisor who can look at your full financial picture and build a mortgage that meets your life needs.

1. Establish your home buying team

Buying a home isn’t something you should do alone. Before you start browsing listings, make sure you have the right people in your corner.

🏦 Mortgage specialist

Connecting with a mortgage specialist is usually a good first step in the mortgage application process. The earlier you connect with them, the more time you have to strengthen your position before you apply. An RBC Mortgage Specialist can help you:

  • clarify the application process;

  • understand what you can realistically afford;

  • walk you through your mortgage options; and

  • get you set up for pre-approval.

Once you find the home you’d like to purchase, a mortgage specialist will work with you to design a mortgage—including the interest rate type, payment frequency and amortization period—that’s right for you.

🏡 REALTOR®

A REALTOR® brings local market knowledge, negotiation experience, and access to listings that can make a real difference in a competitive search. They can help you narrow down your options and guide you through the offer process with confidence.

🔎 Home inspector

Once you find a property you love and are serious about making an offer, a qualified home inspector can help make sure there are no costly surprises hiding behind the walls, in the attic, with the foundation, or with the structure of the home. If you have one in your corner early on, it can help speed up the offer process, too.

⚖️ Your real estate lawyer or notary

They handle the legal side of your transaction like reviewing contracts, managing title transfers, and making sure everything is in order on closing day. In Quebec, a notary is required by law; in other provinces, a real estate lawyer fills this role.

2. Budget beyond the home purchase price

Budgeting is another important element of preparing yourself to apply for a mortgage. Getting pre-approved can give you an idea of what you might be able to afford, which can give you a good starting point.

A budget isn’t just about the purchase price. First-time home buyers are often surprised by how many costs come alongside it like closing costs, home insurance, property taxes, and maintenance.  When you map all of that out upfront, you make decisions with a lot more confidence and a lot less stress.

Just because a buyer is pre-qualified for a certain loan amount, doesn’t mean they’d be comfortable making those mortgage payments at the current interest rate. Make sure you use an online affordability calculator to give you a better sense on where you stand, financially. RBC has their Mortgage Affordability Calculator that can give buyers a sense of the total costs associated with purchasing a home, including heating costs and property tax. REALTOR.ca also has an affordability calculator, making it easy to figure out finances when one listing turns into 20 tabs and a completely new five-year plan.

3. Get pre-approved for a mortgage

A mortgage pre-approval is when a lender formally reviews a borrower’s income, debts, and assets. Pre-approvals are typically valid for three to four months. This is an exciting step in the mortgage application process because buyers can use this information to make serious offers on properties. Some sellers prefer when buyers are pre-approved, as it’s less likely the deal will fall through due to financial issues.

Here’s more information on a pre-approval, including what you need to get started.

Pre-approval is also a great time for buyers to consider the pros and cons of the different mortgage types available to them.

When a buyer comes in pre-approved, the whole process moves faster and with fewer surprises. We’ve already reviewed your income, your debts, your assets. So when you find the right home, there’s no scrambling. The financing piece is handled, and everyone at the table knows it. Just as importantly, a pre-approval also gives you the confidence to house hunt and submit an offer knowing what you can actually afford.

4. Organize your financial statements

First-time home buyers should organize all the necessary financial documents early on in the mortgage application process. Lenders will need this information to process the loan.

The financial documents required typically include:

✓employment and income verification (i.e. copy of recent pay stubs);
✓confirmation of your down payment (i.e. savings or investment statements);
✓a pre-approval certificate; and
✓bank account statements.
Once an offer is accepted, the mortgage application process tends to move swiftly. Having the right documents in place ensures first-time home buyers can finalize their purchase as quickly as possible. It’s also important to secure these documents in advance if a home purchase takes place during a holiday when banks and major financial institutions are closed.

When offering home buying advice to clients, Atwal recommends narrowing the search to homes that align with both lifestyle needs and pre-approved budget.

“It’s about what type of home you would love, as well as what works for your whole financial picture. The clearer you are on that going in, the more confident every decision feels.”

Here’s where the realistic budget comes in handy. A lender may refuse to finance a home if the offer price is higher than what the buyer can afford. Sticking to a budget can help first-time buyers avoid rejection.

While shopping around, buyers should also consider what kind of home they want to live in. Fixer-uppers or unfinished homes have very different financing implications than move-in-ready properties.

Getting the right mortgage can be as important as finding the perfect property. If you’re looking to purchase your first home or property, Eileen or Jesse can help with everything from house hunting to selecting a mortgage specialist.

Read

New property listed in Osoyoos

I have listed a new property at 3 2000 Valleyview Drive in Osoyoos. See details here

Rare Front-Row 3-Bedroom Residence at The Residences at Spirit Ridge! Welcome to the lifestyle you've been dreaming of! This rare front-row 3-bedroom home offers an exceptional opportunity to own in one of Osoyoos' most sought-after gated communities. Showcasing quality craftsmanship and high-end finishings, this fully furnished home features an open-concept layout, beautifully appointed ensuites, expansive accordion glass doors opening to a large covered deck, heated floors, fireplace, gas range, outdoor fire table, BBQ, and double garage. Perfect as a full-time residence, vacation getaway, or investment with short-term rentals allowed, pet-friendly, and no age restrictions. Located above Sonora Dunes Golf Course, owners enjoy a private pool, hot tub, fitness centre, plus access to Spirit Ridge Resort amenities. Leasehold property with NO GST and NO Property Transfer Tax. Rarely do front-row 3-bedroom homes become available—don't miss this opportunity to enjoy luxury resort living in Osoyoos. (id:2493)

Read

Is Your Home Ready to Sell? A Comprehensive Checklist

Getting your home ready to sell can take some work, but it’s worth it to help maximize your opportunity for the best offers possible. Sell it, toss it, donate it. If you haven’t used it in the last six months, it’s got to go. Buyers believe the way they view the home is how they’re going to live in it, so make sure it’s looking as ready as possible!

It’s important to not get overwhelmed by the process. It’s easy to go down a rabbit hole of downsizing and decluttering when you’re looking to list. Your closets and garage do not have to be perfect. Focus on your main living areas and ensure those spaces look fresh and bright.

Consult your realtor regarding essential renovations

Remember: renovations aren’t mandatory when preparing your home to sell

Before you go and spend thousands of dollars on updating your kitchen or bathroom for purely aesthetic reasons when trying to sell your home, check in with your REALTOR® to see if that’s necessary. Everyone thinks you need a new kitchen or bathroom to sell a home and that’s not the case. Many buyers love a house that hasn’t been updated as long as it’s been cared for and clean. A clean home goes a long way!

What to do in the kitchen before listing your home

Even though you may not have to fully renovate your kitchen before selling, you still should make sure it’s in tip-top shape for any walkthroughs or open houses. Keeping the space bright, clean, and organized is crucial.

To get your kitchen ready for selling, clear all surfaces—for photos and showings you want the countertops to be clutter free. Having everything put away shows potential buyers you have enough storage for all of your kitchen appliances and knick knacks.

No one likes cooking or baking in the chaos of a dirty, unorganized kitchen. You’ll have buyers open cupboards to check to see how much storage is available, so try to make sure what they find isn’t off putting. Ensure there are no cooking odours from the day before, and that garbages and recycling bins are empty.

Ask yourself these questions about the kitchen:

  • Refrigerator spotless inside and out? 

  • Is it organized? Spoiled food discarded? 

  • Frost removed in the freezer? Light bulbs working? (Buyers look!) 

  • Oven and  stove top clean? Burner trays cleaned? 

  • Sinks clean? Faucets working properly and leak-free?

  • Garbage disposal in good working condition? 

  • Dishwasher clean and stain-free?  

Ensuring clean and inviting bathrooms

Is your bathroom ready for prospective home buyers to see?

Similar to kitchens, it’s essential for bathrooms to look and smell clean. Shelves should be organized and highlight the amount of space that’s available. New towels should be put out and garbage bins emptied. Make the buyers feel welcome with a scented candle or plug in, but make sure it’s not too strong—that can be off putting as well. The main thing is getting the clutter off the counters just like your kitchen.

Ask yourself these questions about the bathroom:

  • Fresh soap on display?

  • Sinks spotlessly clean, faucets working properly?

  • Tub and shower surfaces clean? 

  • Towels stain-free and hanging neatly?

  • Shower curtains clean and in good repair? 

  • Toilet extra clean and working properly? 

  • Medicine cabinet cleaned out? 

Creating Welcoming Spaces: Minimizing Personal Items for Potential Buyers

Preparing your living room, dining room, and bedrooms before your home hits the market

Your living areas—including living rooms, dens, dining rooms, studies, and bedrooms—need to be inviting to potential buyers, and not overloaded with personal items that detract from the space itself. Sometimes that means finding inexpensive items to replace what you currently have. Staging the furniture to use the space efficiently is key as well. Think of how photos would look.

For bedrooms they need to feel comfortable and relaxing, not chaotic. It’s best to put away most of the family photos, jewelry boxes, etc.—anything that sits on top of a night table or dresser. And, the bed must be made. All of this is an effort to show the person who owns the home is really looking after it and they are on top of things. This impression is carried through to all other aspects of the home, like cleaning, maintenance, and overall care.

Ask yourself these questions about the living room, dining room, and bedrooms:

  • Everything thoroughly vacuumed/dusted? 

  • Excess furniture removed?

  • Remaining furniture clean and in good repair? 

  • Wood and other surfaces clean and polished?

  • Bookshelves neat, organized and clutter-free?

  • Children’s games/toys stored neatly? 

  • Fragile items removed and stored? 

  • Smaller valuables removed/locked away? 

  • Window coverings open for views and sunlight?

  • Mirrors clean and in good repair? 

  • Fireplace clean, logs/kindling stacked neatly?

Maintaining a well-kept yard for a great first impression

What to do with your home’s yard before listing

Outside your home is also important when it comes to selling. Your front yard needs to make a great first impression, and any other yard space should make it easy for potential buyers to envision how relaxing it would be to enjoy. Make sure no kids’ toys are left on the lawn and all landscaping lights are working. Make sure your gate latches are working and functional. First impressions are everything and the exterior of the home is your first impression.

Cut your grass, maintain weeds, remove any debris from the yard. You want people to be able to imagine throwing a ball in the yard and being able to use it in whatever way they may have in mind. You don’t want them to envision how much work they would have to put into it.

Ask yourself these questions about the yard:

  • Driveways and sidewalks clear of snow and ice? 

  • Lawns freshly mowed/edged? 

  • Large bare spots repaired? 

  • Trees pruned, hedges trimmed? 

  • Flower beds weeded and tidy; dead plants replaced?

  • Junk and scrap removed? 

  • Lawn furniture clean, organized, and in good repair? 

  • Bicycles, children’s toys stored neatly?

  • Firewood organized and neatly stacked? 

  • Dog runs secure, yard free of “doggy deposits”?

Commonly overlooked aspects when listing your home

What people often overlook before putting their home up for sale

Cleaning your windows is a big one. Wiping down light switches and baseboards goes a long way, as well. When those things are clean it gives the buyer confidence that other, perhaps more important things, are taken care of. If you have dark bedding, consider replacing it with a lighter colour—it brightens the room and photographs so nicely. 

At the end of the day, Eileen will help ensure your home is in the best shape possible before listing, but there are some things you can start doing in advance to help move the process along.

Read

New property listed in Osoyoos

I have listed a new property at 111 5005 LAKESHORE Drive in Osoyoos. See details here

Imagine waking up to panoramic views of Osoyoos Lake, stepping outside to stroll along your private sandy beach, and ending the day watching the sunset from expansive lakeside decks. Island View Resort offers a rare opportunity to own not only a spectacular waterfront residence, on a commercially zoned property with exceptional future potential. The main residence features approximately 4,800 sq. ft. including 4 spacious bedrooms and an attractive one-bedroom lock-off suite that provides flexibility for guests, extended family, or additional rental income. Large decks surround the home, creating seamless indoor-outdoor living and multiple spaces to relax and entertain while taking in the lake views. The private backyard is a retreat of its own, complete with a charming cottage, hot tub, putting green, and ample space for gatherings. The oversized property offers room for expansion and creative development ideas. Being sold as a strata lot with the home and established business opportunity. Additional income streams include a space a main for small space for shop, guest laundry facilities, and amenities that support the neighboring RV park. The home is fully furnished and turnkey, Island View Resort is ready for immediate enjoyment and operation. Whether you're seeking a lakeside family retreat, a profitable income-producing property, or a unique live-work opportunity, this exceptional waterfront offering delivers the best of Osoyoos living. (id:2493)

Read
The trademarks REALTOR®, REALTORS®, and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are member’s of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.
Powered by: REALTOR.ca